Aging at Home: 7 Signs a Parent May Need Extra Help

Most older adults want to stay right where they are. In AARP’s national Home and Community Preferences Survey, 77% of Americans aged 50 and older said they want to remain in their homes as they age. Staying home works best when support arrives before a crisis forces the decision, so the real skill for families is noticing the early signs that a parent could use extra help. Here are seven worth watching for, along with what to do when you spot them.

1. The Mail and the Bills Are Piling Up

Unopened envelopes on the counter are one of the earliest and most reliable signals. Managing bills takes memory, attention, and initiative all at once, which makes it one of the first routines to slip. If a parent who was always on top of the paperwork now has late notices in the stack, treat it as information rather than a failing.

2. The Fridge Tells a Different Story Than They Do

A parent will often say meals are fine, and the fridge will say otherwise. Expired food, a freezer full of untouched dinners, or noticeable weight loss all suggest that shopping and cooking have become harder than anyone is admitting. Nutrition problems tend to compound quietly, since low energy makes cooking even less appealing the following week.

3. Housekeeping Standards Have Slipped

Look for the difference between a busy week and a changed baseline. Laundry that never gets folded, bathrooms that no longer get scrubbed, and clutter accumulating in walking paths matter both as symptoms and as hazards. Falls remain the leading cause of injury among older adults, and a cluttered hallway raises that risk every single day.

4. Medications Are Being Missed or Doubled

Check the pill organizer if there is one, and count what remains in the bottles if there is not. Skipped doses and accidental double doses are among the most common reasons older adults end up in emergency rooms, and they are also among the most preventable. For a parent with declining cognition, managing five or more daily prescriptions can be quite challenging, and support from home care or a nurse may help.

5. They’re Withdrawing From People and Activities

When driving gets stressful, or energy runs low, social life is usually the first thing to shrink. A parent who has stopped attending church, skipped the weekly card game, or gone quiet with old friends may be struggling with more than mood. Isolation accelerates both physical and cognitive decline, which is why companionship is a core part of most professional care plans rather than an afterthought.

6. Memory Lapses Are Changing Daily Life

Everyone misplaces keys now and then, so occasional forgetfulness is not the signal. The changes worth acting on are the ones that alter routines: missed appointments, repeated questions in the same conversation, a stove left on, or confusion in familiar places. With an estimated 7.2 million Americans aged 65 and older living with Alzheimer’s, early conversations with a doctor matter, because early support can extend the years a person can live safely at home.

7. You’re Exhausted, and You Live With a Knot in Your Stomach

Caregiver burnout is a sign in its own right. If every visit ends with you doing three loads of laundry, and every phone call starts with your heart in your throat, the current arrangement is running past its limits. Care that depends on one exhausted adult child is fragile, however loving it is.

What to Do Once You’ve Seen the Signs

Start with a conversation that centers your parent’s own goals, since almost every older adult shares the same one: staying home. From there, get a professional assessment. Publicly funded options exist across the U.S. through state Medicaid waivers and Area Agencies on Aging, though hours are allocated by clinical priority. Because public support may not cover everything your Family needs, many choose to evaluate home health care vs long-term care options early to map out a complete plan.

Many Families supplement with a private provider such as Integracare senior home care, where an in-home assessment turns a vague worry into a concrete plan, and support can scale from a few hours a week to daily visits as needs change. The right level of help can restore the relationship, too: you get to go back to being a son or daughter instead of a case manager.

Final Thoughts

None of these signs means a parent has to leave home. Each one simply means the current amount of support no longer matches the need, and matching them back up is a solvable problem. Families who act on the early signals get to make decisions calmly, with their parent at the table, which beats making them from a hospital hallway every time.
How Seniors Can Review Their Financial Protection as Their Circumstances Change

There are many changes that a person might experience during retirement. One of the biggest is the change of his income sources and spending as well as family obligations. This is why it would be better for a retired individual to consider the revision of his financial protection from time to time instead of basing it on some decisions that were made years ago.

Reviewing Existing Financial Commitments

A retiree will generally have less money to pay out in obligations as they do not need as much money after retirement, especially if they no longer have a mortgage or any other debt repayments. Nevertheless, they might still have outstanding debts or obligations or those to do with their family or spouse. Looking at all this will help determine which obligations will be hard on their family should the senior no longer be around to provide for them financially.

Any changes within the senior’s family will also impact their financial plans. For example, marriage, divorce, death of a spouse, birth of grandchildren, or taking care of one’s adult children might cause a senior to reassess how he protects his financial interests. This might require a look into their finances or beneficiaries and everything else related to their finances.

Considering Life Insurance Needs

Life insurance could still be useful in some cases for senior citizens where there are dependents or where there is need for shared obligations or estate planning. The coverage level that worked at some point in the past may not be appropriate anymore after retiring from work whereas some senior citizens may realize that there are still good reasons for keeping themselves covered. Various elements such as assets, debts, income and obligations can determine if it makes economic sense to continue purchasing life insurance.

When seniors are thinking about buying life insurance, they should take a look at their financial status rather than just on the policy. Familiarity with various elements of life insurance such as premiums, coverage levels, terms of the policy and financial benefits can help to assess the case properly. Reading information provided on Life Insurance Options for Seniors in Canada could also be helpful for making a decision.

Updating Estate Planning Decisions

Estate planning is another instance in which changes in plans for an elderly individual can occur. The value of property, investments, savings, and other assets will likely shift through time, just as family relations and beneficiaries might differ from when the initial documents were put in place. It would be helpful to review wills, beneficiaries, and other estate documents in order to ensure consistency between them and current intentions.

In addition, financial considerations can fit into more general estate planning considerations. Some elderly individuals might wish to pass on money to their families, donate some money to charity, or even cover costs associated with administering the estate. This review of intentions can allow one to determine whether the current financial plan will satisfy one’s wishes.

Accounting for Health And Lifestyle Changes

Health and changes in lifestyle can influence the way financial planning works when people retire. Any new costs connected with healthcare, changes in living conditions, or the necessity of extra help can impact the ways savings and income are used. Therefore, seniors can find it beneficial to reconsider their financial security when something happens that relates to health, family conditions, or expenditures and should consider when to buy life insurance.

It is also important to pay attention to the moment when financial planning should be done. It is possible that a delay in this process will leave one fewer choice because of difficulties, and a person can have a greater chance to analyze various options when they plan ahead.

The benefit of conducting an evaluation periodically would be to enable the senior to feel more secure about his or her financial planning staying relevant in light of any changes. This may include a retirement situation, changes in one’s family, new expenses, or estate planning.

Caring for Aging Skin After 60: A Gentle Routine for Seniors and Caregivers

Skin changes as we age, and after 60 those changes become hard to miss. It tends to feel drier, look thinner and take longer to bounce back from a scrape or a harsh soap. None of this means skin care has to get complicated. In most cases, the best routine for older skin is simpler and gentler than the one we used at 40.

Here is a practical routine for seniors, and for the family members and caregivers who help them.

Why older skin needs a softer touch

With age, skin produces less oil and holds less moisture. The outer layer becomes more delicate, so products that once felt fine can start to sting or leave skin tight and itchy. Indoor heating, hot showers and long baths make dryness worse, especially in fall and winter.

The goal is simple: clean without stripping, moisturize often, and protect what you have.

Step 1: Wash with lukewarm water and a mild cleanser

Hot water feels good but pulls moisture out of the skin. Lukewarm is better. Choose a fragrance-free or lightly scented cleanser that does not foam heavily, and use it on the face, hands, underarms and feet rather than scrubbing the whole body every day.

Pat skin dry with a soft towel instead of rubbing. For caregivers, this small change alone can make bath time more comfortable.

Step 2: Moisturize within a few minutes of bathing

Damp skin absorbs moisturizer best. Apply a cream or balm right after drying off, while skin still feels slightly soft. Thicker creams and balms usually work better than thin lotions for older skin, particularly on elbows, shins, heels and hands.

Many people prefer plant-based products with simple ingredient lists, such as those made with oils like jojoba, sunflower or olive, and butters like shea. Small, farm-grown brands like Belfiore Herbal are one example of makers that focus on short, plant-based formulas. Whatever you choose, test a new product on a small patch of skin first and wait a day before using it more widely.

Step 3: Protect skin from the sun every day

Sun exposure adds up over a lifetime, and older skin burns more easily. A broad-spectrum sunscreen on the face, neck and backs of the hands is worth using daily, even on cloudy days or short trips outside. A wide-brimmed hat and light long sleeves help too.

Step 4: Keep the air and the body hydrated

A humidifier in the bedroom can ease dry, itchy skin overnight. Drinking enough water through the day supports overall comfort as well. Soft, breathable fabrics like cotton are gentler on sensitive skin than wool or rough synthetics.

Tips for caregivers

  • Check skin gently during bathing or dressing, especially heels, hips and other pressure points.
  • Keep nails trimmed to reduce scratching.
  • Store moisturizer where it is easy to reach, so it becomes part of the daily routine.
  • Make it social. A hand massage with a favorite cream can be a calm, pleasant moment together.

When to call a professional

Some changes deserve a doctor’s look. Contact a physician or dermatologist about any new or changing spot, a sore that does not heal, a rash that spreads, or itching that disrupts sleep.

The bottom line

Good skin care after 60 does not need a long shelf of products. Lukewarm water, a gentle cleanser, regular moisturizing and daily sun protection go a long way. Keep it simple and consistent.

Is Peoria, AZ a Good Place to Retire?

Peoria, Arizona sits on the northwest edge of the Phoenix metro area and has grown into one of the Valley’s largest suburbs, with more than 200,000 residents. It has also become one of the region’s most popular retirement destinations. Retirees are drawn by the sunshine, the active 55+ communities, and a cost of living that stretches further than in Scottsdale or central Phoenix. The short answer is that Peoria is a strong choice for many retirees, as long as you are prepared for hot summers and a car-dependent lifestyle. Here is a balanced look at what retirement in Peoria actually looks like.

Cost of Living and Taxes for Retirees

Living on a fixed income makes cost a top priority, and Peoria holds up well. Home prices have generally been more approachable than in Scottsdale, Paradise Valley, or central Phoenix, and the broader Valley market has cooled from its pandemic-era peak into a more balanced environment. Many retirees sell a home in a higher-cost state and buy in Peoria with money to spare. Arizona’s tax structure also works in retirees’ favor. The state has a flat income tax rate, and Social Security benefits are not taxed at the state level. Everyday costs like groceries and gas track close to the rest of the metro, so housing is where Peoria makes the biggest difference to a retirement budget.

55+ and Active Adult Communities

Peoria offers some of the Valley’s best options for active adult living. In the far north, Trilogy at Vistancia is a resort-style 55+ community with a clubhouse, golf, fitness facilities, and a busy social calendar. Westbrook Village, closer to the center of the city, is an established age-restricted community with golf courses, recreation centers, and hundreds of clubs and activities. The well-known Sun City and Sun City West communities are right next door as well. Retirees who prefer a mixed-age neighborhood can choose from older homes near Old Town Peoria or the many single-level homes in central Peoria subdivisions. Since price points, HOA fees, and amenities vary widely, it pays to tour several communities before committing.

Healthcare Access

Healthcare is one of the most important factors for anyone planning retirement, and Peoria is well served. Major health systems, including Banner Health, HonorHealth, and Abrazo, operate hospitals, emergency centers, and specialty clinics in and around the northwest Valley. Primary care offices, urgent care centers, and outpatient services are spread throughout the city, so most residents are a short drive from routine care. For specialized treatment, the larger medical centers in Phoenix and Glendale are within reasonable reach. Before choosing a neighborhood, it is worth checking which doctors and hospitals are in network for your Medicare or supplemental plan.

Staying Active and Social

Retirement in Peoria rarely feels slow. Golf is a big part of life here, with courses inside the major 55+ communities and public courses throughout the area. The Peoria Sports Complex hosts spring training for the San Diego Padres and Seattle Mariners each February and March, which is a seasonal favorite among retirees and snowbirds. Lake Pleasant Regional Park is a short drive away for boating, fishing, and scenic walks, and the city maintains an extensive network of parks and paved trails. The P83 entertainment district and Old Town Peoria offer restaurants, live music, and community events, while the city’s recreation programs include fitness classes, senior activities, and volunteer opportunities that make it easy to meet people after a move.

Weather and the Snowbird Lifestyle

Peoria’s climate is a major draw from October through April, when sunny days and mild temperatures make it ideal for golf, hiking, and outdoor dining. That is why many retirees spend winters here as snowbirds before deciding to stay full time. Summer is a different story. June through August regularly brings triple-digit temperatures and stretches above 110°F, which can be a real health concern for older adults. Full-time residents learn to plan errands for early mornings, stay well hydrated, and rely on air conditioning. Some retirees handle this by traveling or spending summers in cooler places such as Flagstaff or out of state.

The Honest Downsides

No retirement destination is perfect, and Peoria has trade-offs. The summer heat is the most obvious, and a reliable air conditioning system is essential. The city is car-dependent, and public transit options are limited, which matters for retirees who plan to drive less over time. Growth has brought more traffic and ongoing construction, especially in the north. Retirees who want a walkable, urban lifestyle with frequent transit may prefer areas closer to downtown Phoenix or Tempe.

Who Peoria Works Best For

Peoria tends to suit retirees who want an active, social lifestyle, easy access to golf and the outdoors, and a lower cost of living than the Valley’s priciest suburbs. It is a great fit for snowbirds who want a winter base, retirees moving to be closer to children and grandchildren in the Phoenix area, and anyone who values good healthcare access with big-city amenities within reach. If your priorities are affordability, sunshine, and a community full of people at the same stage of life, Peoria is a very reasonable choice.

Planning Your Retirement Move to Peoria

If you decide to retire in Peoria, timing your move matters. Fall and winter, roughly October through April, are the busiest months as snowbirds and retirees arrive, so booking early helps. Summer moves come with extreme heat, which means early-morning start times, plenty of water, and extra care for electronics, wood furniture, artwork, and anything heat-sensitive. Downsizing from a long-time family home also takes planning, so give yourself time to sort, donate, and decide what will fit in your new space. Working with a local team such as Camelback Moving in Peoria can take a lot of the stress out of the process, especially when you are coordinating a home sale, a new community’s move-in rules, and a closing date at the same time.

So, is Peoria a good place to retire? For most retirees who prioritize value, sunshine, healthcare access, and an active community, the answer is yes. Visit in both winter and summer if you can, tour a few 55+ communities, and you will quickly find out whether Peoria fits the retirement you have in mind.

Working Past 62: How Group Coverage, Reimbursement Plans and Age 65 Fit Together

Plenty of people keep working well into their 60s. Some enjoy it, some are not yet ready to retire financially, and some own the business that employs them. Health coverage is where those choices tend to tangle, because the plan that fit at 58 may not fit at 64. This explainer lays out the main pieces in plain language so you can ask better questions.

Do I Need a Health Insurance Plan Advisor in Phoenix If I’m Still Working in My 60s?

Not always, but an independent advisor is worth considering when your coverage depends on a small employer, self-employed income or an approaching age-65 deadline. Those three situations carry rules that do not line up neatly. Someone who reviews the whole picture can spot conflicts before they turn into gaps in coverage.

In Phoenix, Arizona, JP Health Insurance Advisors helps self-employed professionals, individuals, families and small businesses choose individual, family and small-business health coverage, with dedicated guidance for real estate agents, mortgage brokers, travel nurses and contractors. It is an advisory, not a carrier, so its job is to explain options across the major full-coverage carriers on both the ACA Marketplace and the private market. The firm positions itself as a guide for people who find the health insurance market confusing, which describes many workers in their 60s.

Owners deciding whether to offer a group plan to a team that includes older staff can read about small business health insurance advisors in Phoenix to see how group options, tax treatment and annual renewals are handled. Older employees often shape the answer, because they are the ones closest to a coverage change.

Why Does Turning 65 Change the Picture for Working Employees?

Turning 65 makes the federal health program for older adults available to you, and whether to enroll right away depends on the coverage you already have through work. Staying on an employer plan does not settle the question automatically. Employer size, the type of plan and whether you are an employee or an owner can all change how the two kinds of coverage work together.

The practical lesson is to treat the months around your 65th birthday as a deadline window, not a formality. Missing a window can leave a gap or create a later cost, and the details come from the federal program itself, so confirm them through its official channels. It also helps to ask your plan administrator for a written statement of how your group coverage treats people who become eligible for that program.

How Do Small-Group Plans and Reimbursement Arrangements Differ?

A group plan is one shared policy that the employer sponsors, while a reimbursement arrangement pays employees back for coverage they hold individually. Two arrangements matter most to small employers. The Qualified Small Employer Health Reimbursement Arrangement (QSEHRA) was created by the 21st Century Cures Act of 2016 for employers with fewer than 50 full-time equivalent employees that do not offer a group health plan, and the IRS sets the annual reimbursement limits each year.

The Individual Coverage Health Reimbursement Arrangement (ICHRA) became available for plan years beginning on or after January 1, 2020, under final rules issued by the Treasury Department, the Department of Labor and HHS in 2019. An ICHRA is open to businesses regardless of headcount, and a worker only receives reimbursements while enrolled in an individual health plan. These are general options, and an advisor can explain how each compares with a traditional group plan for a particular team.

Option Who it suits Point for a worker near 65
Traditional group plan Employers offering one shared policy Coverage is tied to the job
QSEHRA Employers under 50 full-time equivalents with no group plan Employee holds own coverage
ICHRA Employers of any size Individual coverage required for reimbursement
Individual Marketplace plan Owners and people without job coverage Enrollment windows apply

What Changes for Owners and Independent Workers?

Owners and independent workers follow a different set of rules than staff do. Reimbursement arrangements pay employees, not independent contractors, and under Internal Revenue Code section 3508 qualified real estate agents are treated as non-employees for federal tax purposes. A longtime agent therefore cannot assume an employer reimbursement will apply and may need individual coverage instead.

Self-employed people may be able to take the self-employed health insurance deduction on Schedule 1 of Form 1040, but not for any month they were eligible for an employer-subsidized health plan, and the deduction is limited to net self-employment earnings. That means a part-time job with a subsidized plan can change the tax picture. A tax professional should confirm how it applies to you.

If you buy a Marketplace plan and take premium tax credits in advance, those credits are reconciled against your actual income on IRS Form 8962 when you file your federal return. Income often shifts in the years before retirement, so it is worth understanding how that reconciliation could work in your case. Eligibility for any credit depends on your own situation.

What Should I Ask Before Leaving a Group Plan?

Ask what ends, when it ends and what replaces it, and get the answers in writing before you give notice. A short list keeps the conversation focused:

  • When does my group coverage end after my last day, and is there a continuation option?
  • Does the plan treat me differently once I am eligible for the federal program at 65?
  • Will leaving open a Special Enrollment Period, and what is the deadline to act?
  • Will my current doctors and prescriptions be covered on the replacement plan?
  • If my employer offers a reimbursement arrangement, what coverage must I hold to receive it?
  • How will the change affect any deduction or credit I plan to claim?

Arizona uses the federal HealthCare.gov Marketplace, where open enrollment for individual plans has run November 1 to January 15 in recent years, and losing other coverage can open a Special Enrollment Period. As of fall 2026, anyone planning a job change heading into 2027 should check those dates now rather than in December.

How Does an Independent Advisor Help Owners and Older Staff?

An independent advisor lays the options side by side, explains how the rules above interact and handles the administrative steps that tend to trip people up. JP Health Insurance Advisors describes its process on its service pages as getting a quote by form or phone, reviewing options, choosing coverage, and then having the team handle the paperwork and enrollment. It also offers a free, no-obligation consultation and quote.

For an owner, that can mean comparing a group plan against a reimbursement approach before committing. For an older employee, it can mean confirming that the coverage being left and the coverage being chosen do not collide on dates. Questions specific to the age-65 federal program are best confirmed through that program’s own channels, and a careful advisor will say so.

Planning the Next Few Years Without Rushing

Coverage decisions in your 60s are rarely about one plan. They are about timing, tax rules and who is responsible for what at each stage. Writing down your questions, collecting answers from your employer in writing and leaving room before each enrollment window will do more for you than any single product choice. A calm, documented approach protects your options whichever path you take.

Beyond Medical Care: What Really Contributes to a Fulfilling Senior Lifestyle

Medical care gets most of the attention when families start planning for a parent’s later years. Appointments, prescriptions, and test results are easy to track, and they feel like the whole picture. Families across Mukwonago often discover, though, that health outcomes are only one part of what decides whether an older adult is genuinely doing well. The quality of a day comes from company, purpose, comfort, good meals, and a sense of control over ordinary choices. Those things rarely appear on a chart, yet they shape how later life actually feels.

Choosing a Living Arrangement That Fits Daily Life

Many older adults reach a point where keeping up a house takes more energy than it gives back, and where a person lives starts to matter as much as the care they receive. Assisted living is still widely misunderstood as the place where independence ends, and that fear keeps families waiting until a fall or a hospital stay forces a rushed decision.

Communities built around daily support offer a middle path, with help available for the tasks that have become hard and the rest of the day left in the resident’s hands. If you’re located in Mukwonago, assisted living facilities can help you find that balance without surrendering the routines, friendships, and small freedoms that make a day feel like your own. That balance is what most families are really searching for once they begin weighing their options.

Company Is as Important as Any Prescription

Isolation does quiet damage. An older adult who goes days without a real conversation tends to eat less carefully, move less often, and lose interest in things that once brought pleasure. Regular company changes that pattern faster than almost anything else. It can be a standing card game, a neighbor who stops by every afternoon, a weekly phone call that never gets missed, or a shared table at breakfast. What matters is that it happens often enough to be expected. People do better when someone notices they were not around yesterday, and that simple sense of being accounted for carries a person through harder weeks.

Having a Reason to Get Up in the Morning

Purpose does not retire. An older adult still wants to be useful, to be good at something, and to have a part of the day that belongs to them. That might mean tending a few plants, mending clothes, teaching a grandchild a recipe, volunteering for a small task that nobody else wants, or keeping up a lifelong hobby at a gentler pace. The activity itself matters less than the ownership of it. When every part of a day is arranged by other people, energy drains quickly. When some of it is chosen, the rest becomes easier to manage.

Movement That Fits the Body You Have Now

Staying mobile protects nearly everything else: balance, sleep, appetite, mood, and the confidence to leave the house. The goal is not fitness in the way a younger person would define it. Short walks, gentle stretching, chair exercises, gardening, or dancing in the kitchen all count, and doing a little most days beats doing a lot once a week. Strength and steadiness fade quickly when they go unused, and they take far longer to rebuild. Consistency, not intensity, is what keeps an older adult walking into a room under their own power.

Meals Worth Sitting Down For

Eating well becomes harder with age, and often for reasons that have nothing to do with appetite. Cooking for one feels pointless. Shopping becomes a chore. Taste changes, and food that once appealed no longer does. Many older adults quietly slide into a diet of whatever is easiest, and the effects show up months later as fatigue, weakness, and low mood. A proper meal eaten with other people solves two problems at once, because it restores both nutrition and the social rhythm that used to come with it. Mealtimes have always been where families catch up, and that does not stop mattering later in life.

Surroundings That Make Independence Possible

A home either supports a person or quietly works against them. Poor lighting, steep stairs, slippery floors, deep tubs, and furniture that is hard to rise from can turn an ordinary day into a series of small risks. Many older adults manage these obstacles by avoidance, using fewer rooms, skipping showers, or staying put rather than risking a trip outside. Good surroundings reverse that shrinking. Grab bars, level entries, bright lighting, comfortable seating, and short distances between rooms give back ground that was lost. Independence often depends less on ability than on whether the space allows it.

Staying Connected to Family and the Wider World

An older adult who still feels part of the family does better than one who feels looked after by it. That means being consulted, being invited, and being kept in the loop on ordinary news rather than only the serious matters. Grandchildren visiting, attending a birthday, going to a service, following a sports team, or keeping up with what is happening around town all keep a person anchored to the present. Families sometimes withdraw from these invitations out of kindness, assuming the effort is too much. More often, the effort is exactly what the person wants, and being asked matters even when the answer is no.

What a Good Later Life Actually Looks Like

A fulfilling later life is not the absence of health problems. Most older adults live with something, and plenty of them live well anyway. What separates thriving from merely coping is whether the ordinary parts of a day still work: someone to talk to, something to do, food worth eating, a body that can get where it needs to go, and a home that cooperates rather than resists. Medical care supports all of this, but it cannot supply any of it. Families who plan for both sides tend to find that their parent is not simply being kept safe, but is still living a life that belongs to them.

Coverage Between Work and Age 65: A Plain Guide for Arizona’s Early Retirees and Part-Timers

Leaving a full-time job in your late 50s or early 60s often brings a quiet worry along with the relief. The employer plan that quietly handled your doctor visits and prescriptions ends, and the next stretch of coverage is now yours to arrange. Many Arizonans in this position cut back to part-time hours, take on consulting clients, or start freelancing, and each of those paths changes what health coverage looks like.

This explainer walks through the choices available until age 65, what is worth comparing, and where a licensed broker fits in. It is general information, not advice about any one situation, and as of fall 2026 the basic questions are the same ones people have always asked.

What Are Your Self-Employed Health Insurance Options in Arizona?

Most self-employed Arizonans choose between a short stretch of continued employer coverage, an individual plan bought on their own, or a plan paired with a health savings account. Which one fits depends on your health, your budget for monthly costs versus surprise bills, and how long you need coverage to last. A consultant who plans to work three more years has different needs than someone who is truly winding down.

Higby Health Insurance, an Arizona brokerage led by a licensed agent, works with healthy people under 65, including individuals, families, the self-employed and small businesses, to find private coverage. Its individual plans are privately underwritten, and coverage depends on the applicant, so some people will not qualify.

Anyone weighing self-employed health insurance in Arizona can see how that kind of coverage is described, including protection for emergency room visits, urgent care, diagnostic tests and hospitalization, along with preventive care such as annual physicals, screenings and vaccinations. That focus on people under 65 lines up with the early retiree’s window.

Freelancers, consultants and sole proprietors all land in the same category here: no employer is paying part of the premium, so the full decision rests with you. That also brings flexibility. You can pick a plan around your own doctors, medications and comfort with risk, instead of accepting whatever a former employer chose.

Why Does Leaving an Employer Plan Feel So Abrupt?

Because the coverage you relied on usually ends on a fixed date, and nothing automatically replaces it. For years, someone else picked the plan, handled enrollment and took the premium out of your paycheck. Now you are comparing options on your own, often while also adjusting to a different income.

Part-time work adds another wrinkle. Some part-time positions come with a plan and many do not, so ask any employer early what is offered and when you would become eligible. Consulting and freelance income, meanwhile, comes with no employer plan at all, which is why self-employed workers shop for coverage themselves.

Timing matters too. COBRA continuation and individual plans each come with their own enrollment rules, so it helps to look at both before the old plan lapses. The Arizona Department of Insurance and Financial Institutions (DIFI) regulates and licenses insurance in Arizona and provides consumer protection, which makes it a reasonable place to confirm that an agent or company is licensed.

How Do the Main Options Compare?

They differ mostly in who sponsors the plan, how long it lasts, and how much your own health matters. The table below gives a rough side-by-side.

Option Typically suits Worth checking
COBRA continuation A short bridge after leaving a job Length of coverage and the full monthly cost
Private individual plan Healthy people under 65 Underwriting results and network
HSA-eligible plan People who want to set money aside for medical costs Deductible level and your cash cushion
Employer arrangement (ICHRA or QSEHRA) Workers at a small business that offers one Whether your employer actually provides it

Higby Health Insurance says it can discuss COBRA alternatives, HSA-eligible plans, and employer arrangements such as ICHRA and QSEHRA, in addition to its private individual coverage. That range is useful because early retirees rarely fit neatly into one category. A person might work part-time for a small employer and still need to cover a spouse separately.

IRS Publication 969 explains that contributing to a health savings account requires coverage under a high deductible health plan. In other words, the account and the plan travel together, so an HSA is only an option if the plan underneath it qualifies. Confirm that a specific plan is HSA-eligible before counting on the account.

Households add another layer. If a spouse is still covered through a job, you may want to compare joining that plan against buying separate coverage. If both of you have left work, you may prefer to make one decision for the household. Either way, ask each option how dependents are handled.

What Should You Compare Before You Choose?

Start with three things: whether your doctors are in the network, whether your prescriptions are covered, and how the deductible fits your cash on hand. A few more checks round out the picture:

  • Networks: Check that your primary doctor, specialists and nearest hospital are included, and confirm with the provider’s office, not only a directory.
  • Prescriptions: Look up each regular medication on the plan’s drug list and note any restrictions.
  • Deductibles: A lower monthly cost often means more out of pocket before coverage pays, so match it to what you could comfortably cover.
  • Preventive care: Confirm that annual physicals, screenings and vaccinations are included, since routine checkups matter more with age.
  • Eligibility: Ask how underwriting works and what happens if an application is declined.

Write your answers down side by side rather than relying on memory. Two plans can look alike on the surface and differ sharply once a specialist visit or a monthly prescription enters the picture.

How Does a Licensed Broker Help?

A licensed broker explains the options, checks plans against your doctors and medications, and helps you apply, so you are not decoding policy language alone. Brokers can compare several plan types, which lets the conversation start from your needs rather than a single product.

For a healthy person under 65, a broker can also explain how underwriting works and whether a health assessment might apply. Higby Health Insurance states on its website that its partners use health assessments to identify low-risk individuals, so a healthy applicant’s own profile can carry weight in the price. Results vary, and some applicants will not be approved, so a candid conversation about your history at the start is useful.

Check the license first. As noted above, the Arizona Department of Insurance and Financial Institutions is the state body that licenses insurance in Arizona, so verifying an agent’s status there is a sensible step before sharing health details. Ask, too, how the broker is paid and who helps if questions come up after you enroll.

Planning Notes as 2027 Approaches

Heading into 2027, a few habits make this transition calmer. Estimate your likely income from part-time or consulting work, since a variable income affects how much monthly cost you can carry. Set a date to compare plans well before your old coverage ends, and keep plan documents in one folder.

Remember that the goal is a bridge to age 65, not a permanent answer. Choose coverage that fits the next few years, and recheck it each year as your health, work hours and budget change. Finally, schedule overdue checkups while the current plan is still active. It is far easier to book routine visits and refill prescriptions before the coverage date passes than after.

Leaving an employer plan early is a common step, and it is manageable with a little structure. Compare networks, prescriptions and deductibles, confirm licenses, and give yourself time. Coverage options and eligibility vary by person, so treat any plan as a match only once the details have been confirmed.

Gentle Movement or Strength Training? Older Adults May Need Room for Both

The recycling bin has wheels, but somebody still has to pull it back up the drive. If that part is getting harder while a half-hour walk still feels fine, walking farther probably isn’t the answer.

The walk can stay. What’s missing is the sort of effort needed to pull, lift, and stand. Older adults don’t have to choose between gentle movement and strength work. They need somewhere in the week for both.

The Pull Back Up

Dragging a bin asks more than walking beside it. There’s weight through the arms, a grip on the handle, and, if the drive rises, a fair bit for the legs to do. The awkward part may last less than a minute, but it tells you where the gap is.

Other jobs give the same clue. The dog-food bag stays in the car until somebody visits. A deep drawer gets opened with a foot because standing again has become a nuisance.

I’d write down the job rather than starting with a list of exercises. “Pull the bin up the drive” is useful. “Get fitter” isn’t much help to anybody.

Two Days, Not a New Life

Twice a week is a sensible place to start. It also lines up with the CDC’s advice for adults aged 65 and older, which includes strength work alongside aerobic and balance activity. The usual walk can stay where it is. So can the gardening, errands, and the odd day when nothing much gets done.

For the bin, a supported row makes sense because it uses a pulling action. Chair rises and a low step give the legs some work. A light carry brings the hands and trunk into it. That’s already a session.

I’d use the same few movements the second time. If five chair rises are comfortable and the next five get untidy, stop at five for now. The number can change later; the chair isn’t going anywhere.

Home Changes the Choice

A gym or class gives you equipment and somebody who knows how to set it. Home removes the trip and the person who notices when a foot is in the wrong place.

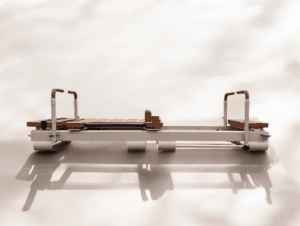
Carriage machines come with muddled names. A Lagree reformer machine usually means slow, demanding resistance work. A Pilates machine can be used more quietly, but neither label tells you how a certain exercise will feel under your body.

For someone who wants both ranges, a Pilates-inspired resistance machine is one way to set up at home. Core Collab’s Sculptformer has a moving carriage, springs, and platforms, and it can be used for controlled movement or harder full-body work. It is the brand’s alternative for Lagree-style training, not an official Lagree machine.

That’s enough about the name. The useful part is whether the machine can be set for the person who’s in the room. On a low-energy day, the range may be smaller and the pauses longer. On a strength day, the springs can ask for more.

The Awkward Bit

Getting onto a low carriage is easy to overlook from a product photo. So is turning from sitting to kneeling, or standing when the session is finished. I’d try those parts with an instructor before worrying about a longer routine.

Ask the instructor to write down the spring settings too. A lighter spring can reduce resistance in one movement and take away support in another, which is not obvious the first time. “Light” and “easy” are not always the same instruction.

Then look at the room. If a cane is used, it needs a place where it can be reached without leaning across the machine. Slippers, a phone cable, and the dog’s bowl can all move. The carriage can’t.

The first few sessions can be three exercises and a bit of practice getting on and off. Finishing early is cheaper than guessing your way through a sore week.

Wednesday

The strength work was Tuesday. By Wednesday morning the legs may feel used, and the usual walk suddenly looks long. Make it shorter. The normal route does not have to be finished.

Easy days have a habit of growing once the body warms up. Ten minutes into a walk, the stiffness has eased, and one more set suddenly sounds harmless. I’d still leave it. The walk did exactly what it was meant to do.

On some days, that lap around the block is enough. On others, there may be room for three carriage movements you already know well. Use the spring settings the instructor wrote down and save the experimenting for another day.

Check the next morning again. If the stairs have become a bigger job, Tuesday probably needs trimming; Wednesday does not need more added to it.

When Something Has Changed

The first session needs a little more thought after surgery, a fall, a dizzy spell, or a change in an ongoing health problem. This is not a good day to guess and hope everything feels fine.

The National Institute on Aging offers useful advice about exercising with long-term conditions, though it cannot answer the personal stuff. Can you kneel comfortably? Is getting down to the floor a bad idea for now? A doctor or physical therapist who knows what happened can give a clearer answer.

Pass that answer to the instructor in the same plain words. “No kneeling yet” is easy to work with. So is “I need the chair beside me when I stand.” Nobody needs to make a big thing of it.

Help from family can stay simple too. Move the footstool out of the way and write the spring settings on a card. Then let the person doing the exercise set the pace.

Thursday Comes Around Again

A few weeks later, bring the empty bin up the usual side of the drive. No stopwatch, extra weight, or steeper route just to make it count.

Maybe the usual pause is still there. Tell the instructor, along with how often the sessions actually happened. An exercise or spring setting may need changing.

Keep the walk. It was doing its job all along. One Thursday, the bin may reach the gate before anyone remembers there used to be a stop halfway.

Leaving the Family Home: How to Plan a Downsizing Move in Mandarin

Mandarin has a way of keeping people. Families settle under the live oaks, raise kids a short drive from the St. Johns River, and twenty or thirty years pass before anyone thinks about leaving. When that day comes, the move ahead is rarely just about boxes. It means deciding what a lifetime of belongings should become when the next home is smaller, simpler, and easier to maintain.

Downsizing is one of the most emotionally loaded moves a household can make, and also one of the most logistically demanding. The good news is that it responds well to planning. Here is how to approach it in a way that protects your time, your budget, and your peace of mind.

Start Earlier Than Feels Necessary

Most people underestimate how long it takes to sort a home that has been lived in for decades. Attics, garages, and hall closets fill slowly and invisibly. A realistic timeline for a large family home is three to six months from the first sorting session to moving day, and longer if the house also needs repairs before listing.

Starting early does two things. It lets you make decisions at a comfortable pace instead of under deadline pressure, and it spreads the physical work across many short sessions rather than a handful of exhausting weekends. Aim for two or three focused hours at a time, one room or one closet per session, and stop before fatigue sets in.

Measure the New Home Before You Sort the Old One

The single most useful document in a downsizing move is a floor plan of the new place with room dimensions. Whether you are moving to a condo in Jacksonville, a patio home in St. Johns County, or an independent living apartment, the square footage will decide far more than sentiment will.

Measure your largest furniture pieces and compare them against the new rooms. A dining table that seats ten may simply not fit, and knowing that early saves the heartache of discovering it on moving day. Many families find it helpful to tape out furniture footprints on the floor of the new space, or to sketch a simple layout on graph paper, before deciding what stays.

Sort Into Clear Categories

Decision fatigue is the enemy of a downsizing move. Keep the choices simple by giving every item one of five destinations:

  • Keep and move: items that fit the new home and get regular use
  • Give to family: heirlooms and pieces children or grandchildren have asked for
  • Sell: furniture and collectibles with resale value
  • Donate: usable items that no one in the family wants
  • Discard: anything broken, expired, or past its useful life

Ask family members to claim heirlooms early and to pick them up by a firm date. Unclaimed items tend to linger in limbo, and the move cannot wait for them. For photographs, letters, and paper records, consider scanning the originals so the memories travel even when the boxes do not.

Plan Around the Florida Calendar

Timing matters more in Northeast Florida than many people expect. Hurricane season runs from June through November, and a named storm can shut down a week of scheduling with little notice. Summer heat and afternoon thunderstorms also make long moving days harder on everyone, especially older adults who will be on their feet directing the work.

If you have flexibility, late fall through spring tends to offer milder weather and more scheduling options. If a summer move is unavoidable, book an early morning start, keep the home cooled throughout the day, and build in a backup date in case weather intervenes.

Protect the Things That Cannot Be Replaced

Downsizing moves often involve items with more meaning than market value: a grandmother’s china, a hand-built cedar chest, framed photographs, military memorabilia. These deserve extra attention. Pack them yourself or supervise their packing closely, label the boxes clearly, and consider transporting the most irreplaceable pieces in your own car.

Florida humidity is also worth keeping in mind if anything will spend time in storage between homes. Wood furniture, documents, and textiles fare best in a climate-controlled unit rather than a standard garage or outdoor storage space.

Know When to Bring in Help

Some families handle a downsizing move entirely on their own. Many more find that the combination of physical labor, emotional weight, and tight coordination is easier with outside support. That support can come in several forms. A senior move manager can help with sorting, floor planning, and coordinating estate sales. Local charities can often schedule donation pickups for larger furniture. And a moving crew experienced with older adults can handle the heavy work while respecting the pace and the feelings involved.

If you are comparing options, look for movers who offer dedicated senior moving services, since those crews tend to understand the extra patience, careful handling, and flexible scheduling these moves require. The National Association of Senior and Specialty Move Managers is a helpful starting point if you want a professional to guide the sorting process as well.

Whoever you hire, confirm that they are properly registered. Florida requires intrastate movers to register with the Florida Department of Agriculture and Consumer Services, which offers a free online lookup, and movers crossing state lines must hold a USDOT number from the Federal Motor Carrier Safety Administration.

Make the First Night Feel Like Home

The most successful downsizing moves end with a new home that feels familiar from the very first evening. Before moving day, pack an essentials box with medications, glasses, phone chargers, toiletries, a change of clothes, and a few comforting personal items. Ask the crew to set up the bed first, then the favorite chair, then the kitchen basics.

Hanging a few familiar pictures and arranging favorite furniture in a similar layout to the old home can make a remarkable difference, particularly for a parent or grandparent who is adjusting to a big change.

A Simple Downsizing Timeline

If you want a starting framework, this one works for most Mandarin households:

  1. Six months out: Measure the new home, invite family to claim heirlooms, and begin sorting the least-used spaces first.
  2. Three months out: Schedule estate sales or consignment pickups, book donation collections, and request moving estimates.
  3. One month out: Finalize the furniture plan, confirm the moving date, and transfer utilities and mail.
  4. One week out: Pack the essentials box, confirm the crew arrival time, and walk through the new layout one final time.

Leaving the family home is a significant chapter to close. With enough lead time, clear decisions, and the right help, it can also be a surprisingly good one to begin.

How Families Can Create a More Comfortable and Supportive Environment for Aging Parents

Watching parents grow older often brings new responsibilities for families. Everyday activities that once seemed effortless, such as climbing stairs, preparing meals, or managing appointments, may gradually become more challenging.

Creating a comfortable and supportive environment for aging parents does not necessarily require expensive renovations or major lifestyle changes. Often, thoughtful adjustments, regular communication, and appropriate assistance can make everyday life easier while helping older adults maintain their independence.

The key is understanding what parents genuinely need rather than making decisions based entirely on their age.

Make the Home Safer Without Changing Everything

A familiar home provides comfort, but certain features may become difficult to manage as mobility, balance, or vision changes.

Families should begin by identifying everyday obstacles and making improvements that address specific concerns.

Focus on Areas Where Accidents Are More Likely

Bathrooms, stairways, bedrooms, and poorly lit hallways deserve particular attention.

Consider these practical changes:

  • Install grab bars near toilets and showers.
  • Remove loose rugs and electrical cords from walking areas.
  • Improve lighting around stairs and entrances.
  • Keep frequently used belongings within easy reach.
  • Use non-slip flooring or suitable mats in bathrooms.

These adjustments can help older adults move around their homes more safely.

Families should also consider an occupational therapist’s assessment when mobility problems make ordinary household activities difficult.

Use Technology to Support Everyday Independence

Technology can help aging parents stay connected, manage appointments, and request assistance. However, complicated devices may create frustration rather than convenience.

The best approach is choosing simple tools that address an actual need.

Choose Devices Parents Can Use Confidently

Video calling devices, medication reminders, and emergency alert systems can provide useful support.

For example, a parent living alone might benefit from a wearable emergency alert device, while someone who frequently misses appointments may prefer a straightforward digital calendar.

More advanced senior care technologies may involve artificial intelligence and specialized computing equipment. Organizations developing such systems sometimes work with a Best AI hardware supplier to source computing components.

However, families should focus on whether a finished product is accessible, reliable, and appropriate for their parent’s needs rather than its underlying hardware.

Encourage Social Connections and Emotional Wellbeing

Physical comfort is only one part of healthy aging. Older adults also benefit from companionship, meaningful activities, and opportunities to make their own decisions.

Families can help by supporting existing relationships instead of expecting parents to depend entirely on relatives.

Make Communication Part of Everyday Life

Regular conversations help families understand changes in mood, interests, or daily challenges.

Some useful approaches include:

  • Schedule regular family calls or visits.
  • Encourage participation in community activities.
  • Support hobbies that match current abilities.
  • Arrange transportation for social gatherings.
  • Ask parents which activities they genuinely enjoy.

A parent who enjoys gardening, for example, might appreciate raised planting beds rather than being encouraged to abandon the hobby.

Consider Digital Activities That Support Connection

Online classes, virtual family gatherings, and accessible entertainment may help older adults participate in activities from home.

Technology providers supporting larger digital care platforms sometimes obtain equipment through GPU wholesale channels for graphics-intensive computing needs.

For families, however, the priority should remain simple access. A basic tablet with large text and clearly labelled applications may be more useful than an expensive computer.

Build Daily Routines Around Comfort and Health

Consistent routines can make everyday responsibilities easier to manage, particularly when parents have several appointments, medications, or household tasks.

Still, routines should offer flexibility rather than make older adults feel controlled.

Support Healthy Habits Without Taking Over

Families can encourage comfortable daily living through several practical measures.

  1. Plan balanced meals around dietary needs and personal preferences.
  2. Encourage appropriate physical activity following medical advice.
  3. Keep a clear medication list and appointment calendar.
  4. Establish comfortable sleeping and waking routines.
  5. Arrange professional assistance when daily tasks become difficult.

Regular medication reviews, appropriate exercise, and vision checks are also important considerations for preventing falls among older adults.

Evaluate Professional Care and Digital Support Services

Sometimes family assistance is insufficient, especially when aging parents require frequent supervision or help with personal care.

Professional caregivers, home health services, and senior living communities may provide additional support.

Look Beyond Technology When Comparing Care Providers

Some senior care organizations use digital records, communication systems, and data-processing equipment to coordinate operations.

Their technical infrastructure may include components such as DDR5 memory in compatible computer systems. However, hardware specifications alone reveal little about the quality of care residents receive.

Families should instead ask how caregivers communicate, how emergencies are handled, and whether residents receive personalized attention.

Checking staff qualifications, care plans, service costs, and family communication policies provides a more meaningful basis for comparison.

Respect Independence While Offering Assistance

One common caregiving mistake is assuming that aging parents need help with everything.

Taking over tasks unnecessarily can reduce confidence and create tension within families.

Discuss Changes Before Making Decisions

Rather than immediately rearranging furniture or introducing new services, ask parents what they find difficult.

Questions such as “Would better lighting make this room more comfortable?” or “Which household tasks would you prefer help with?” encourage collaboration.

Families should also revisit these conversations periodically because care needs can change over time.

Conclusion

Creating a more comfortable and supportive environment for aging parents begins with listening, observing, and making practical improvements.

Safer living spaces, suitable technology, meaningful social connections, and manageable daily routines can help older adults feel more secure while maintaining independence.

Most importantly, families should treat senior care as an ongoing conversation. When parents participate in decisions about their surroundings and daily lives, the support they receive is more likely to reflect their actual needs, preferences, and personal dignity.