Aging with Dignity: How Modern Senior Care, Technology, and Healthy Lifestyle Choices Improve Quality of Life in Later Years

What does a good life look like at 75, or 85, or 95? For many people, the answer is simple: to feel respected, safe, connected, and in control.

Yet aging is often framed around loss and decline. This can leave older adults feeling invisible, or like a burden. But aging with dignity is possible. Better care, helpful technology, and healthy daily choices can improve quality of life at any age. In this article, you will learn what dignity really means, how modern support can help, and simple steps that make later years brighter.

What Does Aging with Dignity Really Mean?

Aging with dignity means being treated with respect and being able to make your own choices. It rests on four pillars: independence, respect, purpose, and connection. When these are present, people feel valued and at ease.

Dignity matters for mental health, self-worth, and happiness. Aging is a natural stage of life, not a failure. Curiosity also helps. Learning new things keeps the mind active at any age.

Reflection: What makes you feel respected?

The Emotional Side of Growing Older

Growing older brings many feelings. Some people worry about their health or fear losing independence. Others feel lonely, grieve loved ones, or struggle with a changing sense of identity. Retirement, loss, or a move to a new home can all shake emotional well-being.

There are bright sides too. Many people gain wisdom, perspective, deeper relationships, and the freedom to focus on what matters most. Short lessons from learning platforms like Overwell can also help people build new skills and understand themselves a little better.

Mixed feelings are normal. Older adults are not one single group, and every journey is different.

How Modern Senior Care Supports Quality of Life

Good care starts with the person. Person-centered care follows each individual’s wishes, routines, and values.

Many people prefer aging in place. Home care, home visits, and simple home changes can help them stay in their own homes longer. When more support is needed, assisted living and memory care can help. Choose with care, visit in person, and ask many questions.

Community and day programs offer social activities that fight isolation. Family caregivers need support and rest too, since caring for someone is hard work.

Signs of good care are easy to spot: respect, listening, clear communication, and real choice.

Technology That Helps Older Adults Stay Independent

Technology can open doors. Video calls and messaging keep families close. Reminders for medicine, online doctor visits, and simple health trackers support daily health. Emergency alert devices, fall detection, and smart home helpers add safety.

Voice assistants, online shopping, and easy banking make everyday tasks simpler. Learning apps and short online lessons keep the mind growing.

To get started, begin with one tool, ask for patient help, and go at your own pace. Stay alert online, too. Be careful with unknown links, calls, and requests for money or personal details.

Healthy Lifestyle Choices That Make a Difference

    1. Move your body. Walking, stretching, balance exercises, and gentle strength work help you stay steady and strong.
    2. Eat well. Choose balanced meals, drink enough water, and enjoy food with others.
    3. Sleep and rest. Keep regular bedtimes and a calm evening routine.
    4. Keep your mind active. Read, solve puzzles, enjoy hobbies, or learn something new.
    5. Stay social. Spend time with friends, family, clubs, volunteer groups, or faith and community groups.
    6. Find purpose. Mentor someone, start a creative project, or give back.
    7. Talk to a doctor before starting a new exercise or diet plan.
  • Reflection: Which small habit could you start this week?

Building Strong Social Connections

Loneliness affects both mental and physical health. The good news is that connection can be simple. Regular calls, group activities, and shared meals all make a difference.

Bridges between generations help too. Young and old have much to learn from each other. Families can include older loved ones in daily life and in decisions that affect them.

Common Mistakes to Avoid

Some habits harm dignity, even with good intentions. Treating older adults like children or speaking for them takes away their voice. Making big care decisions without including them breaks trust.

Assuming technology is too hard for older adults is unfair, since many learn quickly with patient support. Focusing only on physical health while ignoring emotional needs leaves out half the picture. And waiting too long to ask for help or plan ahead often makes things harder.

When to Ask for Extra Support

Watch for changes in memory, mood, weight, or daily habits, and for trouble with daily tasks. These can be signs that more help is needed.

Asking for help is a sign of strength and good planning. Doctors, counselors, geriatric specialists, social workers, and support groups can all guide you. Watch for signs of depression, such as lasting sadness or loss of interest, and seek early help. If someone feels unsafe, contact local emergency or crisis services right away.
A Simple Dignity Checklist

Save these questions for yourself or a loved one:

  • Am I being heard?
  • Can I make my own choices?
  • Do I feel safe?
  • Am I staying connected?
  • Am I doing something that brings me joy?

Aging Well, One Day at a Time

Dignity grows from respect, good care, helpful tools, and healthy daily choices. No one needs to get everything right at once. Patience, curiosity, and kindness matter at every stage of life.

Later years can be full of meaning, connection, and growth. Each small choice, from a phone call to a short walk, supports a better life.

Choose one small step this week, such as calling a loved one or trying a new tool. Then share your thoughts in the comments, because your voice may encourage someone else.
Downsizing Later in Life: Is a Cash Home Sale the Easier Path?

Your home may begin to feel bigger than you’d like.

Too many rooms to keep up with, the yard, maintenance. Maybe it’s time to downsize. You’ll just have to sell your house first.

Selling your house for cash can make the process simpler if there are repairs needed on the home. But sometimes going quicker isn’t the best option.

Table of Contents

  • Start With Your Future Life
  • Sell Your House For Cash
  • Don’t Look At The Offer Price, Look At What You Walk Away With
  • Inherited Homes
  • Questions To Ask When Selling For Cash
  • Downsizing Into An Easier Home To Maintain
  • Final Thoughts

Start With Your Future Life

Downsizing doesn’t always have to mean selling into a smaller home. It can mean selling your house to fit your lifestyle.

Your current home may have too many stairs. Your ideal home could be closer to family or grocery stores. Maybe you want to stop heating all those extra rooms no one is using.

According to the National Association of Realtors’ 2026 study, 16% of older boomer buyers between the ages of 71 and 79 purchased a home to downsize.

Downsizing does not always mean you will spend less. Depending on the home you buy, there can be HOA dues or repairs that exceed your current costs.

Figure out what your next home should look like before selling your house. Before selling, check the next home’s total costs, location, and access to support, and estimate how much money you’ll have left after the sale.

Sell Your House For Cash

When you list your home for sale, you may need to prep your home, take pictures, get showings, wait on offers, inspections, and possibly do repairs for the buyer. They may even need to qualify for a mortgage, which could fall through.

By selling to a cash buyer, you could avoid some of these steps. Some will buy homes as-is, which may mean you won’t need to make repairs before closing. Check the contract for any conditions. Selling to a cash buyer will also eliminate the possibility of the buyer’s mortgage falling through.

It’s not guaranteed that you can sell your home immediately for cash. There are still things to look for when selling your home to a cash buyer.

If there is a direct home buyer that can purchase your home, get a home cash offer and compare it to what a local agent can tell you you’ll get if you list your home. Always get the details in writing.

Just because it’s easier doesn’t mean it will benefit your finances when you’re older.

Don’t Look At The Offer Price, Look At What You Walk Away With

A direct cash buyer may offer less than a buyer looking for a move-in-ready home. They may be offering you less due to the repairs and time, and they will want to make a profit on the home as well.

However, when you list your home, you could incur expenses to make it sellable. Such as paint, landscaping, rent, cleaning, and repairs that are requested by the buyer after an inspection. You could also have to pay your agent and other closing costs based on your situation.

Get a price range from a local agent on what you can expect to receive. Also ask them what your estimated expenses will be. Then ask the cash buyer what their full offer is.

See how much money you can walk away with and how long each process will take.

List your expected sale amount for both scenarios below. Deduct any mortgage, closing costs, repairs, or anything else you know you’ll owe. Write anything you’re unsure of, like what you may receive if you list your home or the cash buyer’s offer changes after an inspection.

Remember you will have expenses on your home while it’s listed for sale. Such as insurance and upkeep. But those costs may still be smaller than the price difference between a cash offer and a listed sale. Compare the net proceeds of each. Do your research.

If your home is in decent condition and you have time, listing your home may be better for you. If your home has major repairs, you may want to sell it as-is.

Inherited Homes

Another situation you may find yourself in is if your parents passed away and left you their home.

Selling an inherited home may take more time than you think. The house could be in probate, need a deed transferred, or require multiple siblings to agree to sell the home.

Selling to a cash buyer will not fix those situations.

Find out who has the power to sign on the sale of your home. You should also know if there is a mortgage, any liens, property tax balance, and the condition of the home. Speak with an estate lawyer or professional who can guide you in your state.

You’ll also want to know what you owe in taxes when you sell your home. In the U.S., an inherited home’s tax basis is generally tied to its value when the previous owner died. Tax on a sale depends on any gain and the rules that apply, so consult a tax professional. Selling your primary residence is taxed differently; consult a tax professional.

Every home situation is different; always figure out what your costs will be.

Questions To Ask When Selling For Cash

If you’re selling your house or your parents’ house, here are some simple questions you can ask a cash buyer.

  • Who is buying your house? Know the buyer’s name, who will be signing, and whether the contract can be assigned to another party.
  • Can they prove they have funds? Ask the buyer for documentation that they will not have to obtain a mortgage to buy your house.
  • Why would they change their offer? Look at your contract and see what will allow the buyer to change their offer. Some buyers will change their offer after they inspect your home.
  • What will you owe? Ask for a list of what you’ll owe at closing. Such as closing costs, taxes, liens, etc.
  • How soon do you have to move out? Know your closing date, when you’ll need to give possession of your home, and what happens if you don’t have a home to move into.
  • Will you need to clear your house of furniture? Some cash buyers may require you to get rid of certain items in your home.

Also ask how long your offer is good for. Don’t rush yourself to sign a contract; you can always have an attorney or someone else who knows real estate take a look at your contract.

Call your closing professional at a trusted phone number to confirm wiring instructions, especially if an email says they have changed.

Downsizing Into An Easier Home To Maintain

When looking for your next home, look beyond the price. You may not want as many bedrooms but instead a one-level home with a smaller yard. Or maybe your home should be near certain services or loved ones.

Know what your total housing cost will be: taxes, insurance, utilities, repairs, and any dues you may have to pay. Also factor in your moving costs and have money saved for emergencies.

Take your time packing your home; donate, sell, or give away the family memorabilia that you can’t live without. Start sorting and packing early so you can meet your agreed move-out date without rushing.

If you plan to use the sale proceeds for your next home, ask the closing professional to explain when and how you’ll receive them. Make sure you have time to move into your new home when you sell yours.

When possible, arrange the next home before agreeing to a move-out date. Check how the timing will work if you need the sale proceeds to make the move.

Final Thoughts

Selling your house for cash can be a great option when downsizing. It can reduce preparation and showings, and a verified cash purchase removes the uncertainty of that buyer needing mortgage approval.

Know your options, ask questions, and compare your net sale amount when selling your house for cash vs. listing your home.

Turning Unused Gold Into Cash in Retirement: A GoldUnion Guide for Older Adults

For many older adults, some of the most valuable things in the house are also the most overlooked. A broken chain in a jewelry box, a set of inherited coins, a ring that no longer fits: these small items often hold real worth, yet they sit untouched for years. In retirement, when every source of value counts, turning that unused gold into cash can be a simple and welcome step.

The first thing to understand is that gold is priced by weight and purity, not by sentiment or the original purchase price. A professional assessment measures the actual gold content, separates solid gold from plated pieces, and applies the current market rate. That clarity matters, because it protects older sellers from being offered a vague lump sum that bears no relation to what the metal is truly worth.

Retirees are sometimes a target for rushed or opaque offers, which is exactly why transparency should come first. A trustworthy dealer weighs each item in front of the customer, explains how the price is calculated, and hands over a written record of the transaction. There is no pressure to decide on the spot and no mystery about how the figure was reached. Anyone who feels hurried should simply walk away.

Because the gold price moves daily, it helps to glance at the current rate before selling. A quick look at the current rate before selling helps the conversation at the counter start from an informed position rather than a guess. When the moment comes, it is worth knowing where to sell unused gold to a dealer who weighs and tests each piece openly and quotes a price tied to the day’s market, rather than accepting a vague lump sum.

The practical process is straightforward. Gather everything that might contain gold, including odd earrings, dental gold and old watch cases, and sort it roughly by color and type. Bring any receipts or certificates, though they are not essential. A specialist will then test each piece, weigh it, and offer a price tied to the day’s market. Reputable firms such as GoldUnion do this in person at local branches, so there is a real place to go and a real person to ask.

For older adults, that human, in-person element is often the deciding factor. Posting valuables to an unknown address can be stressful and risky, whereas handing them across a counter and watching them weighed is reassuring. It also allows questions to be answered on the spot: how purity is judged, why one piece is worth more than another, and what documentation will be provided.

There is also a quiet emotional side to selling inherited gold, and it deserves acknowledgement. Some pieces carry memories that no price can capture, and those are worth keeping. But many others are simply unused metal, and converting them into money that supports day-to-day life can feel freeing rather than regretful. The key is to choose deliberately which items to keep and which to let go.

It helps to know which everyday items are most likely to contain gold. Beyond obvious rings and necklaces, older households often hold gold in places people forget: cufflinks, tie pins, pocket watches, commemorative coins, dental crowns and even old spectacle frames. Costume jewelry is usually plated and worth little, but solid pieces, marked with a purity stamp such as 9ct, 14ct or 18ct, can add up quickly once weighed together. A professional can tell the difference in moments.

Avoiding poor deals is mostly a matter of patience. Reputable buyers never demand an instant decision, never discourage questions and never object to a seller seeking a second opinion. If an offer feels rushed, vague about how it was calculated, or reluctant to put figures in writing, that is a signal to pause. The safest approach is to deal with an established firm that has a physical address, trained staff and a clear, repeatable process for every customer.

Timing and paperwork round out a sensible sale. Because the rate changes daily, selling on a day when the market is strong can make a modest difference, though no one should try to predict it precisely. Keeping the written receipt matters too: it records what was sold, the weight, the purity and the price, which is useful for personal records and for any tax questions that may arise. A tidy paper trail turns a one-off sale into a clear, accountable transaction.

Used wisely, this kind of small, well-informed sale can top up a pension, cover an unexpected bill, or simply tidy up a lifetime’s accumulation. The amounts vary, but the principle is the same at any age: know what you hold, check the current rate, and deal only with someone who shows their working. For retirees sitting on forgotten gold, that combination turns clutter into genuine value.

Aging in Place: Practical Home Upgrades That Make Everyday Life Easier

The familiarity and comfort of a home can be felt for decades, but managing its features as we get older can become difficult. Even small things can become a struggle when you encounter the window difficult to open, a slick floor, or a dimly lit door. Carefully planned renovations can help seniors maintain their independence at home without creating a clinical feel.

Starting with everyday routines is a good place to begin. Note any areas of difficulty, such as opening doors, carrying groceries, reaching light switches, or moving safely between rooms. These instances provide a more practical renovation checklist than a lengthy catalog of trendy items.

Make Entrances Easier to Navigate

Anyone who uses a wheelchair, cane, or walker should have an accessible entry. Look for doors that require a lot of force to open, uneven thresholds, inadequate lighting, and shaky steps.

Many older adults find lever-style door handles easier to grip and operate than traditional round doorknobs. Another option that can make evening arrivals less unpleasant is motion-activated exterior lighting. When stairs cannot be removed, a well-planned ramp or railing can help; still, have qualified professionals evaluate and install any major accessibility changes. 

If the current fittings are difficult to use, it could be worth considering replacing the windows and doors. Families considering established options may weigh the pros and cons of each model, installation service, and upkeep before committing to a major upgrade.

Choose Flooring With Stability in Mind

The flooring should be stable enough to walk on without getting in the way of walkers or wheelchairs. An increased danger of tripping can be caused by loose rugs, curled carpet edges, and sudden changes in floor height.

Maintain clean pathways, fix broken surfaces, and secure or remove carpets that could cause someone to trip. When shopping for new flooring, ask about the material’s slip resistance, cleaning requirements, and how easily a wheelchair or walker can glide across it. Even if a surface looks great in the showroom, it may respond differently when wet or when someone is less stable.

Pay special attention to the bathrooms. Decorative touches take a back seat to functional safety features like slip-resistant floors, sturdy grab bars, and sufficient illumination. Instead of being screwed into drywall, grab bars should be fastened to appropriate structural supports.

Prioritize Materials That Are Easy to Maintain

Low-maintenance materials can reduce the physical labor required to keep a home safe. For older adults who find cleaning, painting, or frequent repairs physically demanding, these materials can make home maintenance easier.

Some window components and home goods, for instance, make use of fiberglass because of the material’s resistance to corrosion and moisture. One of the benefits is that it “Combines durability with minimal maintenance,” although how well it works depends on choice for certain home improvements, the product, finish, and installation.

Don’t assume any material requires no upkeep. Find out what the guarantee covers, how to clean it, and if repairs are easy. A detailed product description may matter less than easy-to-follow care instructions.

Improve Comfort Without Sacrificing Familiarity

Without breaking the bank, you can create a big impact with well-lit spaces, unobstructed walkways, and convenient storage. Choose controls with legible labeling, install nightlights between the bathroom and bedroom, and bring commonly used things up to waist height.

Seek the elder adult’s decision while making important decisions. Although a caregiver may find a modification useful, the person living in the house may find it unnecessary or annoying. The task should be guided by their habits and preferences.

Plan for Changing Needs

Predicting every potential obstacle is not the point of aging in place. Making reasonable decisions today while keeping room for later adaptations is key.

Before starting any structural repairs or accessibility installations, make sure everyone is safe, set a realistic budget, and consult experts. As their needs change, older adults can maintain their confidence and independence in a home that feels comfortable and manageable.

Moving a Parent to Florida: What to Do About the Car

When a parent decides to trade a New Jersey winter for Florida, the adult children usually end up running the project. The apartment or the senior community gets chosen first, then the movers, then the doctors’ records. The car tends to be the last item on the list, and it carries more weight than it seems, because it is tied up with independence, safety and a fair amount of family feeling.

Working through it early, in roughly this order, makes the move calmer for everyone.

Will Mom or Dad keep driving in Florida?

This is the real question, and it is easier to raise as part of a move than at any other time. A relocation is a natural reset. In a new town, with new doctors and a new routine, it is reasonable to ask whether a car is still needed at all.

Some retirement communities in Florida run shuttles to shopping and medical offices, and many sit within a short ride of everything a resident needs. For a parent who has been driving less each year, selling the car in New Jersey and budgeting for rides can be the gentler choice, and it removes a shipping bill, an insurance policy and a registration from the list.

For a parent who drives confidently and wants to keep doing so, Florida’s own rules offer a helpful checkpoint, covered below.

When to move the car

Timing matters more on this route than on most, because the Northeast to Florida run has its own seasons. Four years of order records from SAKAEM Logistics on the Garden State to Sunshine State run, 266 cars in all, make the pattern easy to see. The median price paid in winter, December through February, was about $1,100. In spring, March through May, it was about $825. Summer and fall sat in between, and a month-by-month look at New Jersey to Florida shipping prices by season shows the same swing.

The reason is the snowbird flow. In January, trucks heading south are full and drivers can choose their loads. In spring, the traffic turns north and southbound trucks run light, so a car going to Florida is easier to place. Spring also arrives before hurricane season begins on June 1, which matters to anyone settling a parent on the Gulf or Atlantic coast.

A family with flexibility can save a few hundred dollars just by scheduling the car for April instead of January.

Where the truck can meet the car

Many 55 and over communities in Florida are gated, and many have rules about large commercial vehicles inside. A full car hauler often cannot get past the gatehouse or turn around on a residential loop. Before booking, a quick call to the community office can settle where deliveries of this size are allowed. Often the answer is a nearby shopping plaza or the clubhouse lot at a quiet hour.

The same check is worth doing at the New Jersey end, especially in older North Jersey neighborhoods with narrow streets or in a condominium with a tight garage entrance.

Whoever hands over the car, and whoever receives it, should do a slow lap around the vehicle alongside whoever is hauling it and mark any existing scratches on the inspection report. If the parent will not be there in person, a family member or a trusted neighbor can do it with written permission.

What should, and should not, ride in the car

It is tempting to treat the car as one more moving box. Most shippers let a modest load of household items ride below the window line, as long as it stays light. A few things should never go in it, though: prescription medications, a pill organizer, medical equipment, eyeglasses, hearing aid batteries, checkbooks, the car title and any document needed in the first week in Florida. The car will be out of reach for several days and weather can stretch that. Pills and paperwork should stay in a bag the parent keeps within arm’s reach on the flight or drive down.

Recent moves on this route give a sense of the timing. A Hyundai Elantra went from Clementon to Naples in two days in May for $990, and an Acura RDX went from Saddle River to Vero Beach in three days in January for $1,100.

Florida paperwork as a natural checkpoint

Florida asks new residents to get a Florida driver license within 30 days of establishing residency. A parent exchanging a valid New Jersey license generally does not retake the written or road test, but does take a vision test and a hearing test. For families who have quietly wondered about a parent’s driving, that visit offers an objective, low-drama moment to see how things stand.

Titling and registering the car in Florida requires Florida insurance to be in place first, and an out-of-state vehicle needs its identification number verified on form HSMV 82042, which a law enforcement officer or a licensed Florida dealer can complete. County tax collector offices handle the rest, and many take appointments, which is worth booking for a parent who would rather not wait in line.

Putting it together

A good plan looks something like this. Decide in the winter whether the car is going at all. If it is, book it for spring, confirm where a truck can meet it on both ends, keep anything medical or financial out of it, and set up the Florida license appointment for the first weeks after arrival.

With the season picked, the remaining choice is simply the week that fits the parent’s moving date.

How to Reduce Fall Risks in the Bedroom for Older Adults

Most people picture falls happening on icy steps or a slick bathroom floor. For many older adults, the riskier trip is a short one: the walk from the bed to the bathroom at two in the morning.

That walk happens in the dark, half awake, often in a hurry. The bedroom is where we let our guard down, which is exactly why it deserves a second look. The good news is that most of the fixes are cheap, quick, and need no remodeling at all.

Why the Bedroom Deserves Special Attention

Falls are common, and they are not a minor problem. According to the CDC, more than one in four people aged 65 and older fall each year, and falling once doubles the chance of falling again.

The bedroom stacks several risk factors into one small space. People get up at night when the lighting is poor. They go from lying flat to standing in a few seconds, which can bring on a brief wave of dizziness as blood pressure catches up.

Medications taken at bedtime add another layer. Sleep aids, sedatives, and some over-the-counter remedies can leave a person drowsy or unsteady for hours.

None of this is a reason for alarm. It is a reason to set the room up so that a stumble has less chance of turning into a fall.

Light the Path From Bed to Bathroom

Poor lighting is one of the easiest risks to fix. A lamp or switch should be reachable from the bed without stretching or standing up first.

Plug-in night lights along the route to the bathroom help even more. Motion-activated models switch on the moment someone steps out of bed, so nobody has to fumble for a switch in the dark.

Light the destination too. A soft light left on in the bathroom gives the eyes a clear target and time to adjust before they reach a hard, possibly wet floor.

Clear the Floor

Clutter is a quiet hazard. Shoes, laundry baskets, stacks of books, and pet beds tend to gather around the bed, right where feet land first.

Walk the route from bed to door and from bed to bathroom, and move anything in the way. If a walker or cane is used now, or might be soon, keep the path wide enough for it.

Cords deserve their own check. Lamp, phone charger, and heating pad cables should run along walls or behind furniture, never across a walking path.

Small throw rugs are a common culprit because their edges curl and their backs slide. The simplest move is to remove them. If a rug has to stay, secure it with rug tape or a non-slip pad.

Get the Bed Height Right

The bed sits at the center of the room, and its height matters more than most people realize. A bed that is too low forces the knees and hips to work hard on every stand. A bed that is too high leaves the feet dangling and turns getting in into a small climb.

A useful rule of thumb: when a person sits on the edge of the mattress, both feet should rest flat on the floor with the knees bent at roughly a right angle. That position gives the most stable base for standing up and sitting down.

For someone recovering from surgery, living with limited mobility, or spending long stretches in bed, a fixed-height frame can be a real limitation. A bed that raises for caregiving and lowers for safer transfers solves both problems, and families weighing that kind of setup can compare adjustable hospital beds for home use to see which features fit their situation. Whatever the choice, the wheels should lock firmly and the frame should not shift when someone leans on it.

The mattress matters as well. A very soft edge sinks when someone sits on it, which makes the push to stand harder and less stable. A firmer edge gives a solid launch point.

Add Something Solid to Hold

Standing up is the most unsteady moment of the whole trip. A firm handhold beside the bed makes it far safer.

Assist handles that anchor to the bed frame give something to grip while sitting up and rising. Choose one built for the specific bed and install it exactly as instructed, since the FDA has warned that poorly fitted adult bed rails can trap a person between the rail and the mattress.

Check the nightstand too. People instinctively reach for it when they lose balance, so it should be heavy and stable. Furniture on wheels, or anything that wobbles, should not live next to the bed.

Slow Down the Get-Up

Some of the best fall prevention costs nothing. It is simply a change in how a person gets out of bed.

Sit up first and pause for a few breaths. Then swing the legs over the side and sit on the edge for a moment before standing. That short delay gives blood pressure time to adjust and lets any dizziness pass while the person is still seated.

Footwear matters on the way out. Socks on a hardwood floor are slippery, and loose backless slippers can catch or slide off. Closed-back slippers with non-slip soles are a better choice.

Keep the essentials within arm’s reach of the bed: glasses, a phone, a glass of water, and any needed medications. Every unnecessary trip across a dark room is one more chance to fall.

Plan for the Moment Help Is Needed

Even a well-prepared room cannot remove every risk. A phone or wearable medical alert device within reach means a fall does not have to become a long wait on the floor.

It also helps to bring the doctor into the conversation. A medication review can catch combinations that cause drowsiness or dizziness, and a regular eye exam keeps vision as sharp as possible for those nighttime trips.

For a broader look at the rest of the house, the National Institute on Aging offers a helpful room-by-room guide to preventing falls at home.

Start With One Change Tonight

A safer bedroom does not require a weekend project. Pick the single biggest gap and fix it today.

For most homes, that means a night light on the path to the bathroom, a clear floor, and a bed at the right height. Add a stable handhold and a slower get-up routine, and the most dangerous walk of the night becomes a lot more routine.

Small changes, made before a fall rather than after one, are what keep people living safely and independently at home.

Choosing a Care Facility for a Parent: Red Flags to Watch For

The biggest red flags when choosing a care facility for a parent are short staffing, unanswered call lights, unexplained injuries, poor hygiene, and a facility that is reluctant to share its inspection record. Any one of them deserves a second look, and several together are reason to keep searching.

Most facilities provide attentive care, but when a resident is harmed, families often ask when substandard care causes harm and what options exist. Careful checking before a move is the best way to avoid that situation, and it starts with how a tour is done.

A scheduled weekday tour shows a facility at its best. Visiting again on an evening or weekend, and arriving around a mealtime, shows staffing levels and routines that a prepared tour does not.

What red flags should you look for on a tour?

The clearest warning signs are visible to anyone who walks the halls with attention to detail. Look and listen for these:

  • Too few staff in sight: Few aides on the floor, call lights glowing for long stretches, and residents left waiting for help to reach a bathroom.
  • High turnover: Staff who are new every month, or managers who cannot say how long aides and nurses usually stay.
  • Persistent odors: Strong, lingering smells of urine or neglect that cleaning products do not cover.
  • Residents who look neglected: Unwashed hair, soiled clothing, residents in bed at midday without reason, or people sitting alone in hallways with nothing to do.
  • Signs of physical decline: Bruises or injuries no one can explain, weight loss, dehydration, and pressure sores.
  • Food and water: Meals that sit untouched, residents who need help eating and do not get it, and water out of reach.
  • Defensiveness: Managers who dodge questions, will not share the most recent state inspection report, or discourage drop-in visits.

No single sign proves neglect, and a bad day can happen anywhere. The pattern is what matters: whether the same concerns appear across several visits, and whether staff respond openly when asked about them.

How do you check a nursing home’s inspection record and ratings?

Start with Medicare’s Care Compare website, which rates Medicare- and Medicaid-certified nursing homes from one to five stars based on health inspections, staffing and quality measures. Searching by name or ZIP code pulls up each facility’s recent inspection findings and complaint history.

Ratings are a starting point rather than a verdict. A facility with a strong overall score can still have a weak spot, such as a unit with chronic understaffing, so reading the underlying inspection reports matters more than the star count. Nursing homes that take part in Medicare or Medicaid must make their latest inspection results available to residents and visitors, so asking to see them is a reasonable request.

Comparing at least three facilities side by side, with the same list of questions at each, makes differences easier to see. In Massachusetts, the Long-Term Care Ombudsman Program offers another check. Ombudsmen advocate for residents of nursing and rest homes and investigate complaints, so a call to the local ombudsman can reveal patterns that a website does not show.

What questions should you ask before signing an admission agreement?

Ask how many nurses and aides are on each shift, how often staff change, and how the facility tells families when a resident falls or is injured. The answers show how transparent a facility is, and vague answers are themselves a red flag.

Ask when care plan meetings happen and who attends, how pain and medications are reviewed, and what the facility does when a resident’s needs increase. Read the admission agreement closely for fees, discharge rules and how disputes are handled before signing, and ask a family member or an elder care professional to read it too. Residents and families can ask for time to review before deciding.

Who do you call if you suspect abuse or neglect in Massachusetts?

In Massachusetts, suspected abuse of a patient by nursing home or hospital staff is reported to the Department of Public Health at 1-800-462-5540. Abuse of an adult aged 60 or older living in the community goes to the state Elder Abuse Hotline at 1-800-922-2275, and abuse of an adult aged 18 to 59 with a disability goes to the Disabled Persons Protection Commission at 1-800-426-9009. In immediate danger, call 911.

Writing down what was seen, with dates, times and the names of staff involved, makes any report stronger. Photographs of injuries, copies of the care plan and notes from conversations with staff all help, and a request for a care plan meeting puts concerns on the record.

How can you stay involved after a parent moves in?

Regular, varied visits are the best early warning system. Dropping in at different times of day, including mealtimes, evenings and weekends, shows what daily care looks like when no one expects a family member.

Watch for changes between visits: weight loss, new bruises, a parent who seems withdrawn or unusually sleepy, or changes in medication that no one explained. Attend care plan meetings, ask for updates after any fall or hospital visit, and get to know the aides who provide most of the hands-on care, because they notice changes first. A simple notebook with dates, observations and names of the staff spoken to turns vague worries into facts that can be raised with administrators or reported if needed.

A one-page list of questions, carried to every tour and filled out on the spot, makes facilities much easier to compare a week later.

How Regular Car Maintenance Helps Seniors Drive Longer

Driving gets harder as we get older. Reactions slow down, eyesight isn’t what it used to be, and busy roads can feel more stressful than they once did. That’s why many seniors drive calmly. 

But even the most careful driving style can’t guarantee safety on its own. If the brakes are worn or the headlights are dim, a car can let you down at the worst possible moment. In this article, you’ll learn why regular maintenance matters so much for older drivers and how to take care of your car the right way, so you can keep driving safely for years to come.

Why the Condition of Your Car Matters More With Age

As we get older, our bodies change in small ways that affect driving. Night vision often gets weaker, glare from oncoming headlights becomes harder to handle, and it can take a little longer to react when something unexpected happens on the road. None of this means a person should stop driving. It simply means there is less room for error, and a car in good shape helps make up the difference.

Think about brakes that stop a fraction of a second sooner, headlights that are bright and properly aimed, or tires that grip a wet road instead of sliding. Each of these gives a driver a few extra feet or a few extra seconds, and those small margins are exactly what can turn a close call into a non-event.

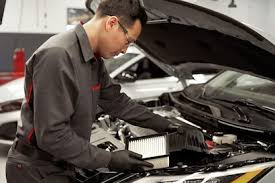
There is also the question of breakdowns. A dead battery or a flat tire is an inconvenience for anyone, but for an older adult alone on the side of a busy road, in the cold or after dark, it can be frightening and even dangerous. Regular maintenance catches most of these problems before they leave you stranded. A couple of times a year, it is worth taking a moment to book a service visit and let a trained technician look over the things you can’t easily check from the driver’s seat.

The Parts That Matter Most for Safety

Brakes come first. If the pedal feels soft, the car pulls to one side when you stop, or you hear squealing or grinding, it is time to have them checked right away. Brakes wear gradually, so the change can be hard to notice from the driver’s seat, which is why a professional inspection is so useful.

Tires are a close second. Worn tread makes it much harder to stop on wet or snowy roads, and tires that are low on air make the car handle poorly. Tire pressure also drops in cold weather, so it is worth checking it more often in the winter months. A technician can measure the tread, look for cracks or bulges, and rotate the tires so they wear evenly and last longer.

Lights and wipers are easy to overlook, but they have a direct effect on how well you can see and be seen. Headlight lenses turn cloudy and yellow over the years, which dims the light on the road at night. Wiper blades harden and start to streak, leaving a blurry patch right in your line of sight. Both are inexpensive to fix and can make driving at dusk or in the rain noticeably less stressful.

The battery is the most common reason a car won’t start, especially on cold mornings. Most batteries last around three to five years, and a quick test during a service visit shows whether yours is getting weak. Replacing it before it fails is far better than waiting for a call to roadside assistance.

Finally, fluids such as engine oil, coolant, brake fluid and washer fluid keep the car running smoothly and protect expensive parts from damage. Topping them up and changing them on schedule is routine work for any service department.

How Often Should You Service a Car You Don’t Drive Much?

Many retirees drive far fewer miles than they did during their working years, and it is natural to assume the car needs less attention as a result. In practice, the opposite is often true. Short trips around town never let the engine fully warm up, which is harder on the oil and the battery than long highway drives. A car that sits for days at a time can also develop low tire pressure, a drained battery and rubber parts that dry out. And if keeping a car in shape starts to feel like more trouble than it’s worth, many independent living communities offer scheduled transportation, so residents can still get around without driving every day.

That is why most manufacturers recommend service based on time as well as mileage. Even if you only drive a few thousand miles a year, it is a good idea to have the car looked at about every six months, or at least once a year. The owner’s manual lists the exact schedule for your vehicle, and a dealership service department can tell you what is due based on its age and history.

A simple habit that works for many people is to tie service visits to the seasons, with one check in the fall before the cold weather arrives and another in the spring. That way nothing gets forgotten, and the car is always ready for the conditions ahead.

Getting Ready for Winter

Winter is the hardest season on both cars and drivers. Cold temperatures weaken batteries, thicken fluids and lower tire pressure, while snow, ice and early sunsets make the roads more demanding. A fall checkup is one of the most valuable things an older driver can do.

Before the first freeze, it makes sense to have the battery tested, the tires checked for tread and pressure, the coolant inspected so it protects the engine in freezing weather, and the heater and defroster tested so the windows stay clear. Fresh wiper blades and a full reservoir of winter washer fluid are worth adding too.

It also helps to keep a small winter kit in the trunk with a blanket, a flashlight, an ice scraper, a phone charger and a bottle of water. You will probably never need it, but it brings real peace of mind on a cold evening.

How Families Can Help Without Taking Over

Adult children often worry about a parent who still drives, but they don’t always know how to bring it up. Car maintenance is a gentle and respectful place to start. Offering to keep track of service dates, driving along to an appointment or simply asking how the car has been running feels supportive rather than controlling, and it keeps the conversation focused on the car rather than on the person’s abilities.

Riding along now and then is also a natural way to notice if anything has changed. If a parent seems unsure at intersections, gets lost on familiar routes or has new dents and scrapes on the car, it may be time for a calm, honest talk and possibly a visit to the doctor or a driving evaluation. Many communities offer refresher courses for older drivers, and some insurers give a discount for completing one.

The goal is not to take away the keys but to help a loved one keep driving safely for as long as possible. When families and older drivers approach it as a team, those conversations become much easier.

Choosing a Service Center and Keeping Costs in Check

For older drivers, a good service experience is about more than the repair itself. It helps to choose a place that explains things clearly, gives a written estimate before starting any work and doesn’t pressure you into extras you don’t need. A comfortable waiting area, a shuttle or loaner car, and the option to schedule online or by phone can make the visit much easier.

Dealership service departments know your specific make and model well, use parts designed for your car and keep records of past work, so they can remind you when the next service is due. Independent shops can also do excellent work. Whichever you choose, staying with the same place builds a history that helps technicians spot problems early.

Regular maintenance is also one of the best ways to save money. Replacing worn brake pads costs far less than repairing damaged rotors, and a timely oil change protects the engine from expensive wear. Before your appointment, it helps to write down anything unusual you have noticed, such as a new noise, a warning light or a change in how the car handles. Don’t hesitate to ask the technician to explain what they found and which repairs are urgent and which can safely wait.

Staying on the Road With Confidence

Driving well into later life is about more than skill behind the wheel. It is also about having a car you can trust every time you turn the key. Regular service keeps the brakes, tires, lights and safety systems working the way they should, which gives older drivers the extra margin they need and fewer surprises along the way.

A checkup twice a year takes only a little time, but it protects something that matters a great deal: the freedom to go where you want, when you want. For seniors and the families who care about them, that peace of mind is well worth the effort.

Injured After 65: What Seniors Should Know Before Filing a Claim

When your body is injured, it can affect many aspects of your day-to-day life – whether it be cooking after breaking your wrist or months of physical therapy after breaking your hip.

You begin to wonder: How will you pay for these things? What will your retirement do for you if you’re injured? Did you have these issues before the accident?

There are some things to consider if you are over the age of 65 when you’ve been injured. According to the CDC there were approximately 4.5 million emergency department visits in 2024 from falls by those 65 and older. While not all of these accidents will result in a claim, if you were hurt due to someone else’s negligence, you should look into your options.

Table of Contents

  • Identify Who Caused Your Injury
  • Document Everything and Get Medical Attention
  • If You Already Had Injuries What Can You Do?
  • Your Settlement Should Not Only Cover Hospital Bills
  • Understand Medicare and Insurance
  • Why the First Settlement Offer Needs a Careful Review
  • You Have Time Limits Even After 65
  • Final Note

Identify Who Caused Your Injury

Just because you got hurt does not mean someone is liable to pay you for your injuries. Typically a personal injury claim will need to show that another person or company was negligent and their negligence caused you harm.

If you slipped and fell on a wet floor at the grocery store there are a few things to ask yourself. How bad was your injury? Did the store know the floor was wet? Did they do anything to prevent customers from falling?

This question will go with any injury that happens on someone else’s property or if you were involved in a car accident. There are always going to be questions as to who was at fault and what happened.

Meshbesher & Spence out of St Cloud, MN discuss these types of scenarios on their website meshbesher.com/practice-areas/st-cloud-personal-injury-lawyer.

You may even want to ask yourself if you did anything wrong. States have different laws that allow for you to be partially at fault for your own injuries and decrease the amount you receive. So make sure to document what happened instead of guessing.

Document Everything and Get Medical Attention

Your health is number one. Sometimes when you are injured you don’t know what’s wrong with you. Get medical attention if needed and listen to the professionals that will be helping you.

Make sure you start documenting everything that happens to you.

Some things that may help in a claim:

  • Medical appointments, prescriptions, PT etc.
  • Pictures of your injury and where the accident took place
  • Witnesses and police/incident reports
  • Taxi, Uber, equipment and paid help at home

Write down things you can no longer do due to your injury. If you were injured at a business, report the accident and ask if they have incident reports or security camera footage.

Writing down notes after you leave your appointment can also be helpful.

If you have someone helping you collect information make sure it is still focused on what you have to say.

If You Already Had Injuries What Can You Do?

If you are over the age of 65, chances are you have some type of injury that you have lived with for a long time. Insurance companies will look at your past medical records to see what you may have had before the accident.

Just because you may have had a previous injury doesn’t mean that you can’t get compensation for a new injury.

Try to document what you were able to do before the accident and what you can’t do after. Maybe you were able to walk to the grocery store with a stiff knee but now you require a walker. Or maybe your lower back has always hurt but now it’s preventing you from sleeping and requiring more treatments.

Were you able to climb stairs, go shopping or see your family before your injury?

Use your doctor’s notes, past medical records and describe your life before and after the accident. Make sure to be honest about your prior injuries. You want to show what injuries you have acquired from the accident and if any previous injuries have gotten worse.

Your Settlement Should Not Only Cover Hospital Bills

It’s easy to look at your current hospital bills and want that amount back. But your injury may continue to worsen over time.

You may not have been working if you’re retired so lost wages may not be something to worry about. But what about losing the ability to bathe yourself, cook, drive or visit friends?

There are many factors that can play into a settlement for your injuries. From medical bills, future medical bills and out of pocket expenses. You may be able to receive compensation for your pain and what you can no longer do. This isn’t true for every type of case.

Will you need more PT? Are you unable to drive? Is your spouse taking care of you?

Keep a note of any family that is helping you out as well. Depending on your case you may be able to collect for this time.

Understand Medicare and Insurance

If you have Medicare paying for your bills you should know that you may not receive the full amount of your settlement. Medicare may make conditional payments for accident-related treatment and later seek repayment if a responsible insurer or other primary payer makes a settlement payment.

Before settling, check whether Medicare has a repayment claim and what amount, if any, may need to be repaid. There may be other insurances that can affect your settlement as well.

Always make sure you know what you’re receiving in your settlement. There may be amounts being taken out of your settlement to pay back insurances or attorney’s fees.

Save all correspondence with insurance companies as well. If they ask you to record a statement or sign a medical release, know what you are getting into.

Why the First Settlement Offer Needs a Careful Review

You may want to accept a check as soon as possible to cover your medical bills and get back to your normal life.

Settlement offers can come in early and you may not know how much you’ll recover from your injuries. When you accept a final settlement, you generally give up the right to bring further claims against the other party for the same accident.

If further medical costs are likely, check whether the offer accounts for them before deciding whether to settle. Make sure you know how much is being paid back to insurances and if you are releasing them from your claim.

Always ask for the offer in writing and if you don’t understand it ask them to explain it to you. There may be a time frame listed on your offer that isn’t the statute of limitations to file a claim.

Sometimes settling is the best option for your case but know what you’re getting before you decide.

You Have Time Limits Even After 65

You want to wait until you feel better to file your claim. Just don’t wait until the statute of limitations runs out.

In Minnesota, many negligence-based personal injury lawsuits have a six-year filing limit, but other claims have different deadlines. Medical malpractice claims generally have a four-year filing limit. Some claims against municipalities may require notice within 180 days after the injury or loss is discovered, subject to exceptions. There are many exceptions to these time frames.

So don’t assume you have 6 years to file your case. There are many things to consider when filing your claim and talking to an insurance company does not protect your right to file a lawsuit.

You want to make sure you get information as soon as possible. Cameras get wiped, people move and forget things. So by contacting an attorney you are not settling your case you are just learning what you can do.

Final Note

You shouldn’t have your claim diminished just because you are over the age of 65. Make sure you know what you can do to better your situation and learn more about your claim.

How Medicare Liens Affect Injury Settlements for Seniors

If Medicare paid for treatment related to an injury claim, it may seek repayment when the case settles. Once you agree to your settlement, you think you will receive that money in your pocket, but if Medicare paid for any of your injuries, you may have to give some of that back.

This is where many older people become confused. If Medicare made related payments, it’s possible the recovery amount should be checked before settlement funds are distributed. An early estimate can change.

The 2026 Medicare Trustees Report estimates that 62.2 million people aged 65 or older were enrolled in Medicare during 2025. For seniors pursuing an injury claim, Medicare’s repayment rules may affect the final payout. These are the people who will need to be aware of this if they are seeking compensation for an injury.

Here’s what this guide covers:

  • What is a Medicare Lien?
  • You Will Not Receive Your Full Settlement Amount
  • Medicare Lien Review and Payment
  • Can You Lower the Amount Medicare Wants Back?
  • Things to Keep in Mind With Injury Claims
  • Make Sure to Protect Your Settlement

What is a Medicare Lien?

As stated above, a lien is a term used when discussing your settlement. Medicare refers to it as a recovery amount.

When someone is waiting for an insurance company to respond to their claim, Medicare may pay for some of those services. Medicare may make conditional payments for injury-related services that another insurer is ultimately responsible for.

Once that person receives a settlement, judgment or any form of compensation, Medicare can seek repayment for what they paid.

Say you are an elderly person who got in a car accident. Medicare could pay for your hospital bill while the at-fault party’s insurance is looking into your accident. Once your accident settles, you would need to look at those Medicare payments.

Medicare does not seek repayment for every visit in a person’s medical history. Its recovery claim concerns relevant payments tied to the injury or condition involved in the settlement.

You Will Not Receive Your Full Settlement Amount

Settlement amounts will vary for every individual. Just because your settlement amount is $80,000 does not mean you will walk away with $80,000. Medicare, your attorney, medical bills, etc all play a factor in how much you receive from your settlement.

Use that example of $80,000. Your Medicare payment information shows that Medicare paid $12,000 for services that may have to do with your accident. This does not mean that you will receive $68,000 in your settlement. There may be other services that need to be checked and your attorney fees, expenses, etc. will have to be taken out as well.

If you are living in the Dallas area and dealing with an injury, the attorneys at Freese & Goss can help you with your personal injury claim. No matter who you hire, make sure they know how much Medicare could want back from your settlement.

You want to know this information because you may not receive close to your settlement amount once all liens and expenses are deducted.

Medicare Lien Review and Payment

By knowing how Medicare collects money from settlements, you can avoid receiving money too soon or getting a bill in the mail at a later time.

Notify Medicare about your claim

Whether it is you, your attorney, or your representative, you should let the Benefits Coordination & Recovery Center (BCRC) know that you are involved in a claim that may involve liability, no-fault, or workers’ compensation insurance.

They will use this information to look at your file and see what payments Medicare made for your accident. If you have someone representing you, they can also access the Medicare Secondary Payer Recovery Portal to see your case information. The BCRC will need documentation that someone is representing you before they release that information.

Review your payment information

Medicare will send you a list of payments that they feel may relate to your case. This is only a preliminary amount; they can send you a bill for more after this review is completed.

Look at the information on your list of payments. The dates, what kind of treatment, and why that person went to that appointment are all important things to look at. Maybe that person went to their doctor for something unrelated to their accident; don’t assume that all of those payments were because of your accident.

You can dispute payments that were not related to your accident. You may need medical information and an explanation to back this up.

Report your settlement information

After your case has settled, you will want to report that to Medicare along with the amount you received and any attorney fees/expenses. Medicare may identify more related payments and issue a demand for the amount it says must be repaid.

You may also be able to do a Final Conditional Payment process before your case settles if you meet the requirements. You will need to be timely with this process, so don’t wait until the last minute.

Pay your bill or dispute

Once Medicare sends you a demand, you will want to know your options to either pay or dispute that amount. Make sure you don’t miss the due date on that demand; they may start charging you interest if you don’t pay your bill within that time frame, even if you are disputing it.

You should withhold some of your settlement money until Medicare has resolved their lien against you.

Can You Lower the Amount Medicare Wants Back?

Yes, but it is not as easy as you may think. Just because you are older and retired, or received less money from your settlement, Medicare is not going to lower their bill for you automatically.

You need to ask yourself two questions.

Did Medicare only bill you for payments that are related to your accident? You should review their claim to make sure that all the payments are related to your accident. If not, you may be able to dispute those payments.

Were your attorney fees and expenses factored into the demand? Medicare considers qualifying attorney fees and other costs paid by the beneficiary when calculating the amount it seeks to recover, using specific deduction rules. They follow certain guidelines when calculating this; it’s not something you and your lawyer can decide on.

You can always dispute your demand if you believe that Medicare billed you incorrectly. You can also request a waiver if you meet certain criteria, but Medicare cannot process a waiver until they have sent you a demand.

Just remember, the BCRC handles Medicare Part A and B claims. The BCRC process covers Original Medicare Parts A and B. Medicare Advantage and Part D plans are responsible for recovering any payments they are entitled to seek separately.

Things to Keep in Mind With Injury Claims

Some of the biggest settlement issues come from people thinking that someone else will handle their Medicare bill.

Don’t fall into these mistakes:

  • Taking your settlement too soon – You could receive more Medicare claims after you receive your first payment information.
  • Ignoring Medicare payments that aren’t related to your accident – Always review your list of payments and make sure they have to do with your accident.
  • Spending your settlement right away – You may need that money to pay Medicare if they send you a legitimate bill.
  • Other health coverage and Medicare plans – Check whether a Medicare Advantage plan, Part D plan, Medicaid, or another insurer may have a separate repayment claim. Make sure those are looked into as well.

You also want to keep in mind future medical bills. Medicare may bill you for past services, but you will also need to think about what medical bills you may have in the future. Workers’ compensation settlements have specific Medicare set-aside guidance for future care. Ordinary liability settlements do not use that same CMS review process, but future medical expenses still deserve attention.

Make Sure to Protect Your Settlement

When you receive a settlement, you want to use that money to better your life from what your injury took from you. If you are older, make sure you do your due diligence to protect your money.

Get your Medicare payment information updated, dispute any payments that aren’t related to your injury, review the likely repayment amount before settling, and resolve the final Medicare demand when it arrives. If you do receive a demand, make sure to get that resolved by the deadline.